At first glance, there was nothing to investigate.
The money had left the bank.
That is usually where a business owner stops looking. The tax payment shows up in the bank feed, the bookkeeper marks it, the tax professional says everything was handled, and everyone moves on to the next thing.
But in this case, that bank withdrawal was not the end of the trail.
It was the beginning.
Federal prosecutors in Georgia recently charged Diane Marie Poe, the owner of Genuine Financial Services, with allegedly taking money from clients for bookkeeping, payroll, tax preparation, and tax payments and failing to perform some of that work. According to the Justice Department, at least 26 people were involved, many of them self-employed truck drivers.
Some clients allegedly gave the firm money that was supposed to go toward estimated taxes, payroll taxes, or trust-fund taxes.
Prosecutors say some of it never made it there.
Poe has been charged, not convicted, and the allegations still have to be proven in court.
For me, though, the interesting part of the case is not the indictment.
It is the missing step.
Someone sent money for taxes.
The money left.
And apparently nobody caught quickly enough that the IRS had not received it.
That is a control problem.
The referral made her feel safe
According to the government’s account, many of the clients came through referrals.
That detail jumped out at me.
We tend to think fraud starts with someone shady. A weird email. A fake company. A stranger making promises that sound too good to be true.
Sometimes it starts with:
“My friend uses her.”
That is a completely different kind of trust.
A truck driver tells another truck driver, “She does my books.”
A business owner asks around in a Facebook group.
Someone says, “I’ve worked with her for years.”
And just like that, the normal skepticism disappears.
There is nothing wrong with referrals. They are how most good professional relationships begin.
But a referral is evidence that somebody liked the provider.
It is not evidence that your tax deposit arrived.
Those are two different things.
Then I would look at who controlled the paperwork
This is where the file gets more interesting.
The same firm allegedly handled several pieces of the financial process.
Bookkeeping.
Payroll.
Tax preparation.
Tax filing.
Potentially the tax money itself.
That is convenient for the business owner. One person knows everything. One office handles everything. Fewer emails. Fewer people to deal with.
It also means one provider may be in a position to create most of the evidence the owner sees.
Think about that for a second.
The provider calculates the tax.
The provider tells you what you owe.
The provider gets the money.
The provider files the return.
Then the provider tells you everything was done.
Where is the outside check?
If I were reviewing this after the fact, that is exactly what I would be looking for.
Not another report from the same provider.
I would want something the provider could not create.
In this case, that something is the IRS record.
Follow the money one more step
Here is the habit I would want every business owner to adopt:
Do not stop at the bank withdrawal.
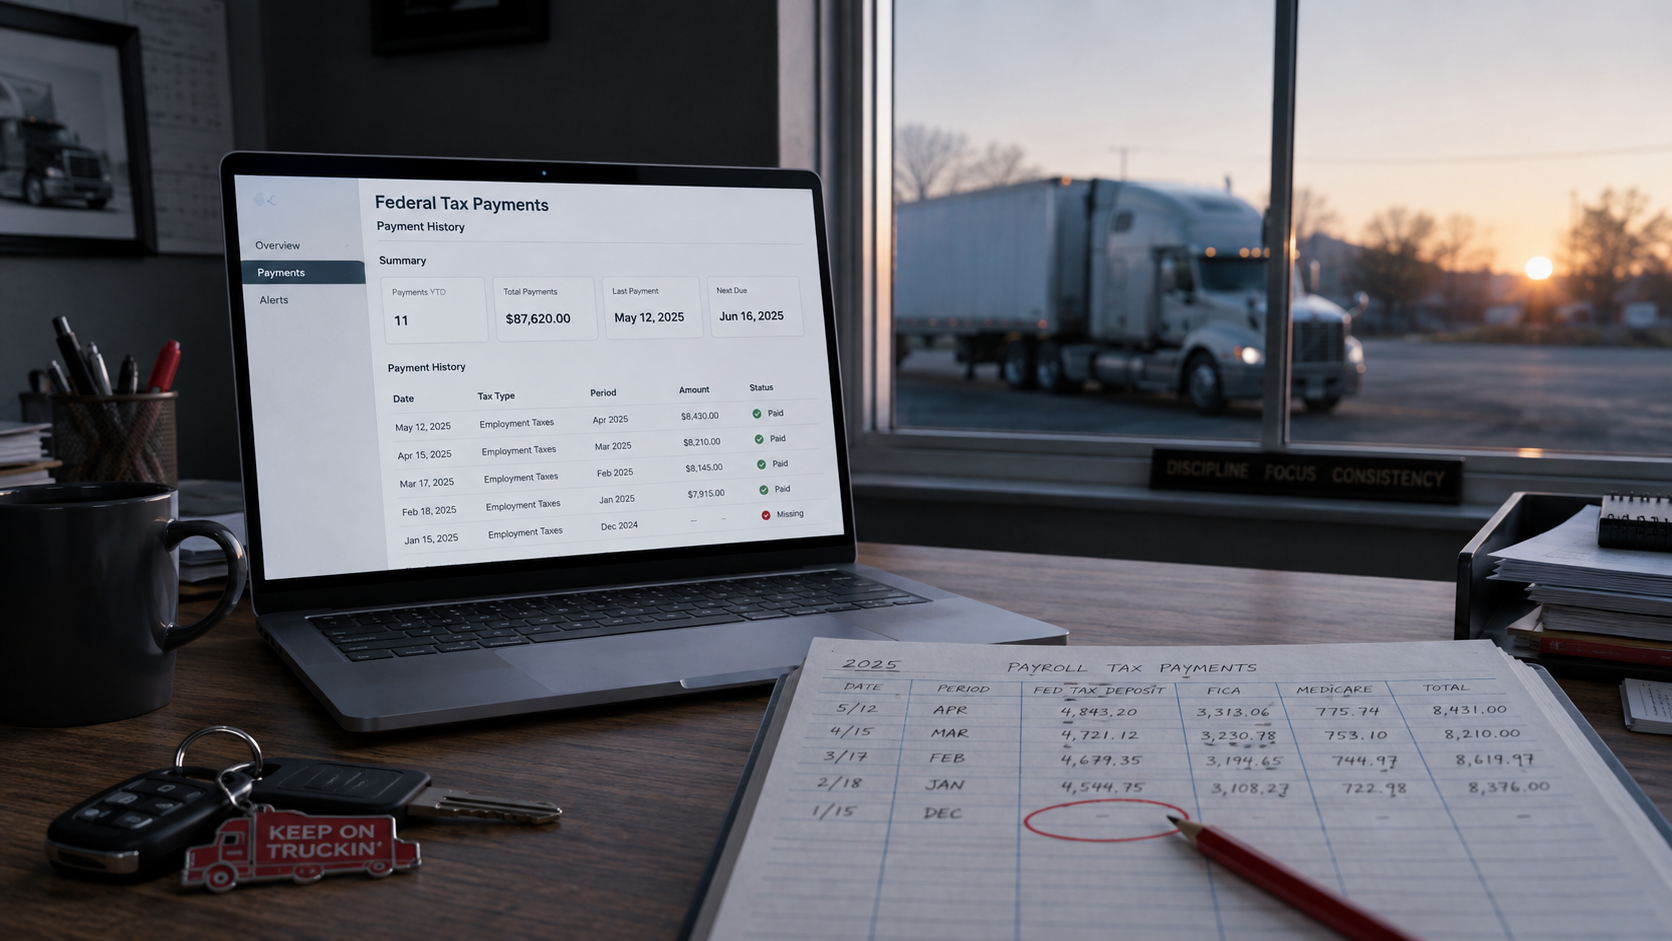
If $8,700 was supposed to go to the IRS, I want to see three things.
The payroll records say $8,700 was due.
The bank shows $8,700 left.
The IRS shows $8,700 arrived.
Now I can close the file.
If the first two are there and the third is missing, I have a problem.
That is why business owners should keep their own access to EFTPS, the Electronic Federal Tax Payment System, even if someone else is making the federal tax deposits.
You are not logging in because you want another bookkeeping chore.
You are logging in because EFTPS is the independent witness.
Your tax professional can tell you a payment was made.
EFTPS can tell you whether the IRS received it.
I care a lot more about the second answer.
The explanations matter too
A missing payment does not immediately equal theft.
Things happen.
Payments get rejected. Account numbers are entered incorrectly. Websites malfunction. Deadlines get missed.
What I would watch is what happens next.
Suppose you ask about a missing payroll deposit.
First you hear:
“The IRS hasn’t posted it yet.”
A week later:
“There was an issue with EFTPS.”
Then:
“We’re going to catch it up with the next payment.”
Now I am asking for documents.
Show me the original confirmation.
Show me the rejection.
Show me when it was resubmitted.
Show me where the money is now.
A legitimate mistake usually leaves a trail.
Fraud has a habit of producing stories.
That distinction matters.
I would also look for control of the mail
Here is another small detail that can turn into a very big one.
Where do IRS notices go?
If they go directly to the business owner, an unpaid tax notice has a chance of being caught.
If they go to the same person who was supposed to make the payment, the owner may never see the warning.
That is a control I would change immediately.
Your tax professional can receive copies.
Your payroll company can receive copies.
But I would not give away the only mailbox.
The same goes for logins.
You should have access to your own tax accounts.
You should be able to retrieve your own returns.
You should not need permission from the person you are checking on.
What would make me dig deeper?
A few things.
A provider who cannot produce a filed return.
A tax payment that appears in the books but not with the IRS.
Repeated excuses about missing confirmations.
Notices that somehow never reach the owner.
Tax withdrawals that are lumped together with service fees so nobody can tell exactly what was paid.
A provider who gets defensive when you ask to see EFTPS.
None of those proves fraud by itself.
But I would not ignore them either.
Fraud investigations are rarely about finding one giant clue.
Usually, it is five small things that did not make sense until somebody finally put them next to each other.
If you find a missing tax payment, stop relying on the same source
This is important.
If the person responsible for making the payment cannot show you where the money went, do not ask that same person to be your only source of information about what happened.
Pull the records yourself.
Bank statements.
EFTPS history.
Payroll reports.
Copies of the tax returns.
Emails.
Invoices.
Payment confirmations.
Engagement letters.
Anything showing what was supposed to happen and what actually happened.
Then bring in someone independent if you need help sorting it out.
A CPA.
A tax attorney.
Another payroll professional.
Your bank.
Your insurer.
Law enforcement, if the facts point that direction.
The IRS also has a process for reporting tax-preparer misconduct, including situations involving employment-tax funds.
But first, preserve the paper trail.
Because once people know you are asking questions, records have a funny way of becoming harder to find.
The lesson is not “do your own taxes”
That would be the wrong takeaway.
Good business owners delegate.
They should.
But delegation and verification are not opposites.
You can hire someone to calculate the taxes.
You can hire someone to file the return.
You can hire someone to send the payment.
Just keep one independent way to prove it happened.
The bank withdrawal is not enough.
The bookkeeping entry is not enough.
The email saying “paid” is not enough.
Follow the money until you can see where it landed.
That is when the file is closed.